You earn more than you ever expected to. The account still feels thin. The anxiety didn’t go away. It just got bigger numbers attached to it. More income was supposed to solve the problem. It turned out to be a louder version of the same question.
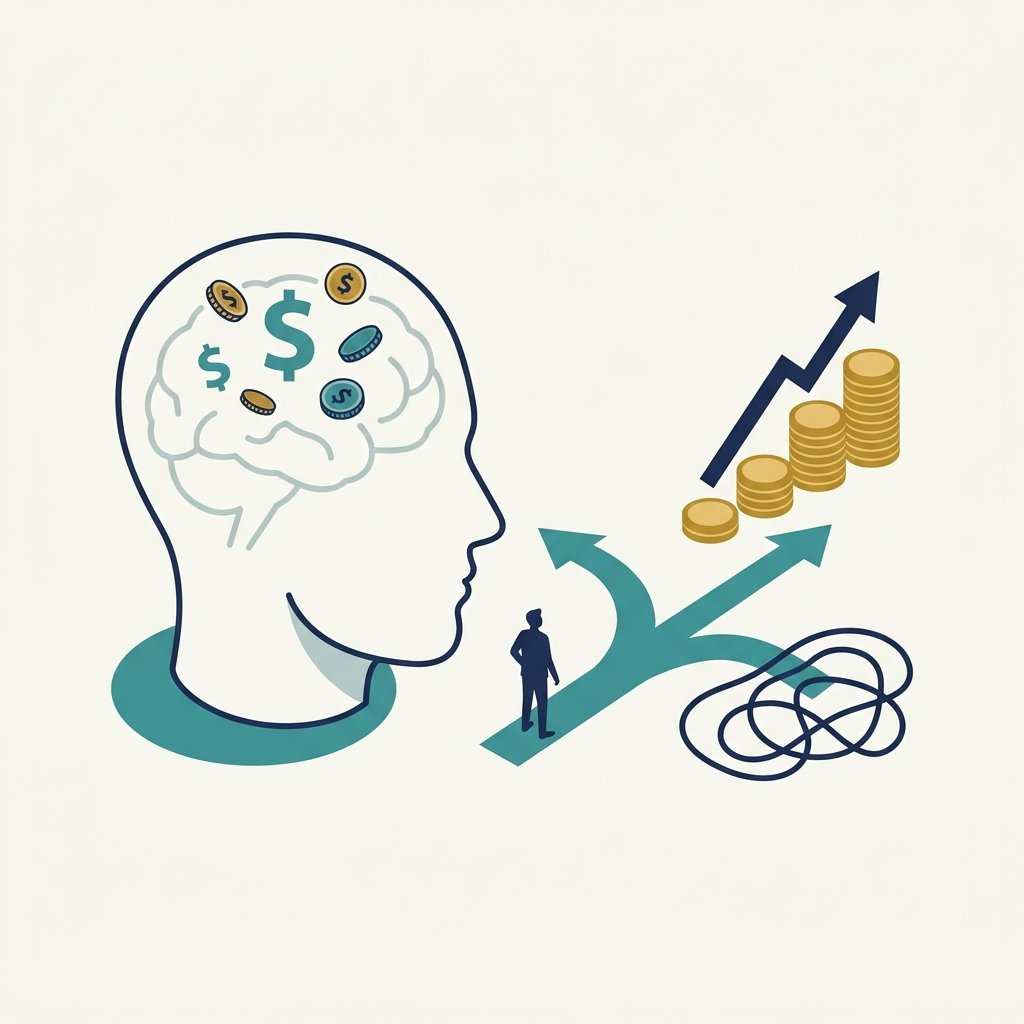
Income and wealth are not the same thing. The space between them is not mathematical. It’s psychological. That’s what the psychology of wealth is actually about, and it’s the part nobody mentioned when the salary went up.
Most advice about building wealth is obsessed with the mechanics: what to invest in, how much to save, which account to open first. It assumes the bottleneck is information. For a specific kind of person, the one earning well and still not building anything, that assumption is wrong, and this guide is about the part underneath it.
What is Psychology Of Wealth?
It’s the study of why income and net worth diverge. Why smart, capable, high-earning people end up with less to show for it than the numbers suggest they should. Not the what of money. The why underneath the what.
Thomas Stanley spent years researching actual millionaires for The Millionaire Next Door, published in 1996. What he found cuts against most of what people assume: high income and high net worth are far less correlated than expected. Most millionaires are not high earners. Most high earners are not millionaires. The gap between those two facts is where the psychology of wealth lives.
That gap isn’t filled with bad math. Nobody sits down, calculates that spending everything is the optimal strategy, and proceeds accordingly. The gap gets filled with identity: what a person believes they’re supposed to do with money once it shows up, a belief usually formed long before there was any real money to test it against. [Why High Earners Stay Broke] walks through that specific divergence in more detail, including the four patterns that tend to drive it.
Money mindset vs. psychology of wealth
These two terms get used almost interchangeably, and that causes real confusion, because they’re answering different questions.
Money mindset is the broader foundation: the full set of beliefs running underneath every financial decision a person makes, regardless of income. It’s the operating system. [What is Money Mindset] covers that foundation in full, including where those beliefs actually come from.
Wealth psychology is one specific, narrower situation sitting inside the larger system: what happens when someone already has enough income that the math should work, and it still doesn’t. It’s not asking why people make bad financial decisions in general. It’s asking a more pointed question: why does earning more sometimes fail to produce more, and occasionally produce less?
Think of it this way. Money mindset explains why two people earning the same modest income end up in completely different places after a decade. Wealth psychology explains something stranger: why a person earning three times the median income can end up with less to show for it than someone earning a third of what they make. If you’ve lived that second situation, specifically, this is the post built for it.
The Janitor Who Quietly Built Millions
Ronald Read spent most of his life pumping gas and sweeping floors. He worked at a service station in Vermont for about twenty-five years, then took a part-time job as a department janitor that lasted into his seventies. He drove an old car and kept wearing a coat held together with safety pins long after most people would have replaced it. Nobody who knew him casually would have guessed what was actually happening with his money.
When he died in 2014 at ninety-two, his real estate turned out to be worth close to eight million dollars. He’d built it slowly, buying shares in solid, familiar companies over decades and never selling out of nervousness or impatience, letting the holdings compound while he kept living exactly the way he always had. He left most of it to his local hospital and library. His story, documented at the time by outlets including the Wall Street Journal and the Washington Post, became something of a case study in what patience actually looks like in practice. (Source: Ronald Read, Wikipedia)
No inheritance funded it. No windfall, no lucky tip, no extraordinary income at any point. Just a small, unglamorous paycheck and decades of not interrupting the thing that was working.
Now hold that next to the more familiar version of this story: someone earning two or three times what Read ever made, with almost nothing to show for it, twenty years in. Same available math. Wildly different outcome. The difference isn’t intelligence, and it isn’t even getting renegotiated by comfort, status, or a new idea of what he deserved. That’s the whole subject of wealth psychology in a single life.
There’s a distinction worth naming directly here. Making money is a flow: it requires showing up, continuously, for it to keep arriving. Building wealth is a stock: assets that exist and keep growing whether or not you show up tomorrow. What separated Read wasn’t skill at the flow. It was a handful of unglamorous habits repeated for decades: paying himself first instead of last, consistently buying assets instead of experiences, thinking in decades instead of paychecks. [Why Some People Build Wealth and Others Just Make Money] breaks down exactly what separates the two skills, since they’re almost never taught as different things in the first place.
Three Things The Psychology Of Wealth Actually Studies
Three patterns show up consistently in people who earn well but don’t build. Each maps to a deeper post in this cluster, so this is just the intro.
The identity gap. This is the distance between your actual financial position and the financial identity you’ve been carrying since long before the number changed. Identity doesn’t form from a single good year. It forms from years of repetition, which means it updates on a completely different timeline than a bank balance does. The brain also weighs old evidence more heavily than new evidence, especially anything tied to scarcity or instability early on, so one solid raise doesn’t get to outvote a decade of a different self-concept. The income moves. The internal narrator keeps running the old script anyway, because nobody ever consciously sat down and rewrote it. [The Identity Gap: Why Earning Well Doesn’t Feel Like Being Wealthy] goes deep on why that gap forms and what it actually takes to close it.
The invisible ceiling. Most people carry an unconscious upper limit on what they’re allowed to build, set early and rarely examined. High earners hit this ceiling at a higher dollar figure than they used to, which can make it look like progress. But the reset still happens at the new ceiling. The money finds a way out. The mechanism just looks more expensive and harder to spot, because the numbers involved are larger and easier to justify.
The proof problem. This is spending as validation instead of spending as needed. The purchase becomes evidence that the long hours were worth it; you worked hard, so you’re allowed the nice thing. That logic is genuinely true, up to a point. The problem is that it runs on repeat. The nice things keep needing to get nicer to produce the same effect, and at some point, the work itself starts mostly funding the proof that the work mattered, rather than funding anything that outlasts the proof.
Where It Comes From
None of this appeared from nowhere. Three forces tend to build it, usually stacked on top of each other rather than acting alone.
A sudden income jump is the most common origin. The paycheck arrives faster than the identity and habits underneath it do. Most people never consciously close that gap. They just keep operating on the financial habits built on a third of their current income, with three times the money flowing through the same unchanged system. The money scales. The behavior doesn’t. At least not on its own.
The social environment reset happens more quietly. High earners cluster with high earners, and what counts as normal spending recalibrates upward without anyone deciding it should. The dinner that felt extravagant at twenty-five is just dinner at thirty-five. Nobody announces the shift. It just happens, and by the time you notice, the new baseline is already the water you’re swimming in.
And then there are the inherited beliefs about wealth itself, the same money scripts covered in [What is Money Scripts?], applied specifically to accumulation. What you believe about people who build real wealth determines whether you’ll allow yourself to become one. If wealthy people are greedy in your internal rulebook, the brain quietly makes sure you never fully become one. Not from logic. From a kind of protection that’s been running below awareness since you were old enough to absorb the idea in the first place.
I noticed my own version of this the first time I got a real raise, the kind that actually changed what was possible rather than just covering rising costs. I didn’t spend it. I also didn’t save it, not really. I just let it sit, untouched, in checking, for almost four months, like I was waiting for someone to tell me I was allowed to do something with it. Nobody ever does. That’s usually the moment the ceiling shows up, not as a thought, but as a strange kind of paralysis around money that’s just sitting there, doing nothing, because no one ever taught you what “more than enough” was supposed to feel like.
How The Psychology of Wealth Shows Up in Real Behavior
The patterns above are abstract until you see them in motion. Here’s what they actually look like once they’re attached to a real decision.
Lifestyle inflation.
Every raise is consumed before it has a chance to compound. The standard of living rises to meet the income every single time, which leaves nothing behind to actually build with. From the inside, it never feels like recklessness. It feels reasonable: the money’s there, so the upgrade makes sense. The apartment, the car, and the flights all get justified individually, and each justification holds up fine on its own. It’s only at the end of the year, looking at what actually accumulated, that the pattern becomes visible [Lifestyle Creep: How Smart People Slowly Spend Everything They Earn] goes deep down on why this is so hard to catch from inside your own decisions.
The income plateau.
This is the one that catches people off guard, because it runs against what they expected to feel. Earning more, feeling no more secure. The anxiety scales right alongside the salary, so the dread three days before payday doesn’t go away as the number gets bigger. It just gets dressed in a more expensive outfit. People in this pattern often describe a raise that brought zero relief, sometimes even more pressure, since the new number now comes with new expectations attached. [Why Getting a Raise Triggers Anxiety Instead of Relief] explains exactly what’s driving that disconnect.
Investing paralysis.
This is knowing exactly what to do with the money and still not doing it, and the distinction matters: it isn’t confusion. Someone stuck here can usually explain index funds, compound interest, and dollar-cost averaging without much trouble. What’s actually happening is a psychological resistance dressed up as procrastination, and it stays invisible for years, specifically because procrastination is such a comfortable, low-stakes word for what’s really going on. [The Psychology of Investing Fear: Why You Know You Should But Don’t] gets into the mechanism underneath it.
Status spending.
This is buying the appearance of wealth instead of building the actual thing. The external markers- the car, the neighborhood, the bag, the dinner- start to feel like requirements rather than choices, almost like a uniform that has to be maintained. Debt accumulates quietly underneath it, because admitting financial strain feels like admitting something worse than the strain itself. [Why Your Brain Prefers Looking Wealthy Over Being Wealthy — and What That Costs You] breaks down how that loop forms and why it’s so self-sustaining once it’s running.
What the Psychology of Wealth Doesn’t Fix
Worth being direct about this before getting into how actually to use any of it.
If income is genuinely insufficient, meaning what comes in doesn’t cover what survival actually costs, there’s nothing left to work with no matter how it’s allocated, that’s a structural problem, not a psychological one. No amount of identity work fixes a wage that doesn’t cover rent. Pretending otherwise isn’t motivational. It’s just inaccurate, and it puts the responsibility in the wrong place.
Wealth psychology applies to a specific, narrow situation: people who earn enough that math should work, and somehow it still doesn’t. People who already know what they should be doing and keep not doing it anyway. People who have real access to resources and still feel perpetually behind despite that access. If that’s genuinely your situation, the inner work is worth doing, not because it fixes everything on its own, but because an unexamined belief about money is expensive, and you’re already paying for it whether you look at it or not.
How to Actually Use It
Four starting points, not a complete system, and not meant to replace actual financial planning, but each one has a real mechanism behind it rather than just being advice that sounds right.
Separate income from identity first.
Your salary is not your net worth, and your net worth is not your worth as a person. Until those three things are clearly separate in your own head, money keeps doing emotional work it was never designed to do. Write down what wealth actually means to you specifically, not the number itself, but the actual freedom it’s supposed to buy, and see whether the answer matches how you’ve actually been spending. Most people find a gap here worth sitting with.
Build one automatic system before anything else.
One transfer. One investment account set to fund itself without your involvement. One decision made in advance, so the moment of choice never arrives to be litigated every payday. Start there, and only there, before adding anything more complicated. The brain needs one small, repeated experience of money not moving before it can believe that money is allowed to stop moving. Most people skip this step because it feels too small. It isn’t.
Watch where money goes emotionally, not just literally.
The budget tracks the what? The emotional pattern tracks the why, and that’s the part that actually predicts what happens next time. A $400 dinner with colleagues isn’t a spending problem if you actually wanted to go. It is one if you went because saying no felt like failing behind. Same transaction on the statement, completely different driver underneath it, and only one of those two actually needs fixing.
Give the new behavior time to become evidence.
The psychology of wealth doesn’t shift from a single insight. This article includes. It shifts from small experiences that accumulate against the old pattern. Save a little. Leave it alone. Check the account a month later. Nothing catastrophic happens. The brain files that as new information. Do it enough times, and the old script starts losing its grip, not because you decided it would, but because the evidence underneath it finally stopped holding up.
FAQs
What is The Psychology of Wealth?
The study of why income and net worth diverge. Why smart, capable people earn well and still don’t build. It’s the psychological layer underneath the financial one, the reason knowing more information alone doesn’t fix the pattern
Is the Psychology of Wealth different from Money Mindset?
Money mindset is the foundation, the beliefs running underneath all financial behavior, regardless of income. The psychology of wealth is what happens specifically when someone has a decent income but still can’t build on it. One is broad. The other is precise, and it’s about one particular pattern.
Can you earn a lot and still have poor wealth psychology?
Yes, and that’s exactly the point of the whole topic. High income is one of the better disguises for poor wealth psychology that exists, because the paycheck covers the symptoms for a long time before it stops being able to.
Does this mean high earners are bad with money?
Not bad. Unconscious. The pattern that keeps income from becoming wealth is usually running below awareness: inherited habits, beliefs nobody examined, spending that’s doing emotional work the earner doesn’t fully realize it’s doing. “Bad with money” implies a choice being made on purpose. This is closer to a system quietly running on old instructions nobody updated.
Why does this happen more to high earners specifically?
Partly because the stakes look smaller from the outside. A modest earner overspending by a few hundred dollars shows up immediately. A high earner overspending by a few thousand dollars can go unnoticed for years, because the income keeps covering for it. The pattern is often the same. The runway before it becomes visible is just longer.
How long does it take to change the psychology of wealth specifically?
Longer than one article and shorter than forever. Beliefs that formed fastest, often absorbed from a single sharp incident, can sometimes crack fastest too, once they’re actually named. The ones reinforced quietly over the years usually take longer. Consistent small behavior change is what actually moves them. Insight alone rarely does.